A well-informed and intelligent reader of this report who also happens to dislike China to make an understatement, recently sent me some comments following my friend Kevin Duffy’s friendly words about China’s technological progress in last month’s report.
The said reader noted that, “While Latin America and other areas are interesting in the short run, the coming world-wide debt collapse will be led by CHINA despite their stealing every technology they can.”
Needless to say, I completely disagree with this reader. When it comes to inventions and innovations, China has made valuable contributions to civilization. The biochemist, historian of science and sinologist Joseph Needham (1900 – 1995), initiated the publication of the multivolume Science and Civilization in China (1954 – present). To date there have been seven volumes in twenty-seven books. The series was on the Modern Library Board's 100 Best Nonfiction books of the 20th century. Needham's work was the first of its kind to praise Chinese scientific contributions and provide their history and connection to global knowledge in contrast to Euro-centric or America-centric historiography. I did not read all the 27th volume of Needham’s work but a summary of his books, which provided me with some valuable insights. [According to Needham, China made four meaningful inventions: Compass, Gunpowder, Papermaking, and Printing.]
My friend Kevin Duffy added some comments about the ongoing wave of Chinese Innovation under the title, The Quiet Rise of Chinese Innovation
Duffy writes: “Over the weekend, I traded notes with Marc Faber - global investor and editor of The Gloom, Boom & Doom Report. One snippet from our chat set the tone: At major market tops, it isn’t uncommon to see the formation of anti-bubbles alongside bubbles. And those anti-bubbles can bottom when the bubbles peak. In fact, some of the greatest buying opportunities can take place at major tops such as 2000. If you look at some of the Old Economy rejects, the cheapest many of them ever got over the past 30 years was in March 2000.
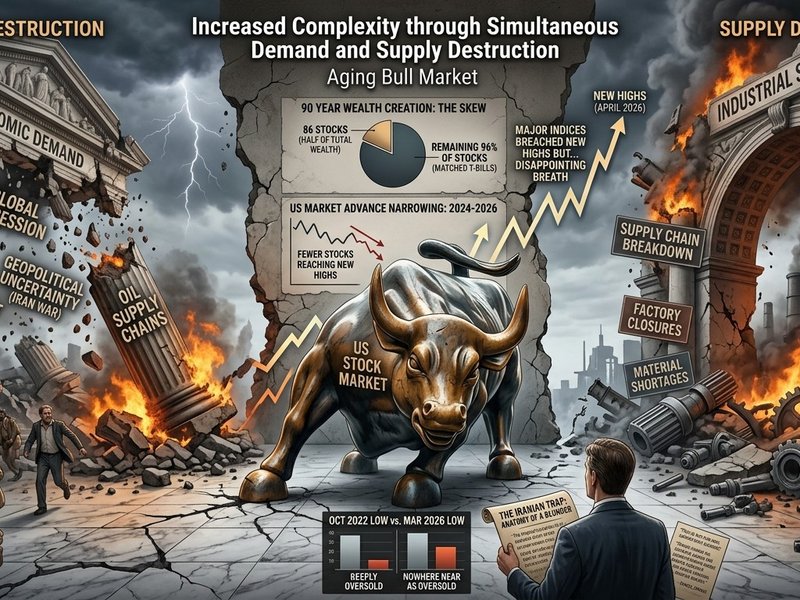
This rings especially true right now. We’re witnessing one of the greatest collective delusions in modern history: American exceptionalism. It’s the unshakable conviction that the United States remains unmatched in technology, military power, democratic government, economic vitality, and cultural influence. Hubris and an aura of superiority run deep.
Meanwhile, the real story unfolding is the anti-bubble: China.”
I am bringing this up because I manage a portfolio of Swiss stocks. Compared to Swiss bond yields (0.385% on Ten-Year Government bonds), stocks are reasonably priced and many mid-sized Swiss industrial companies, having declined by more than 50% over the last few years, look rather attractive. But when I think of future Chinese competition in their fields of expertise, I am deeply concerned about their economic future. I believe that these companies have “some” value because they might be taken over but I cannot see how they could grow much in the current economic environment. [I own some of these companies because of their relatively high dividends.]
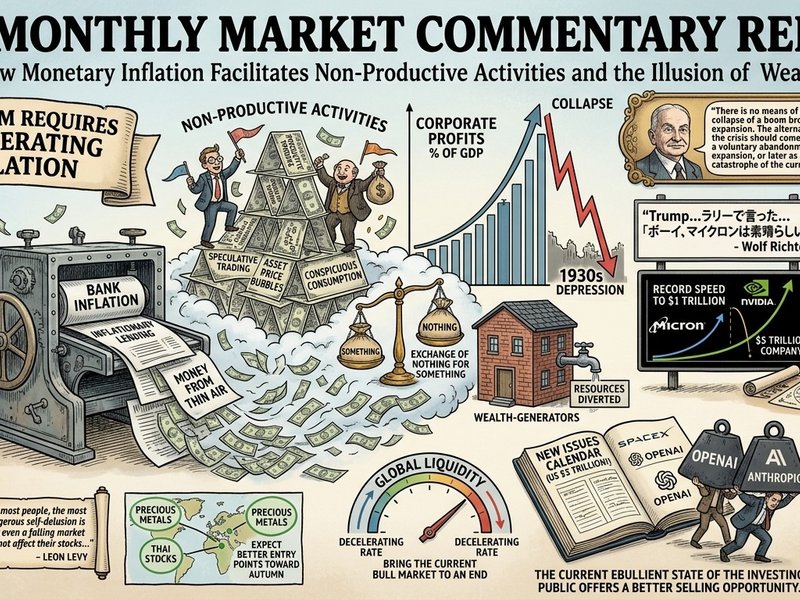
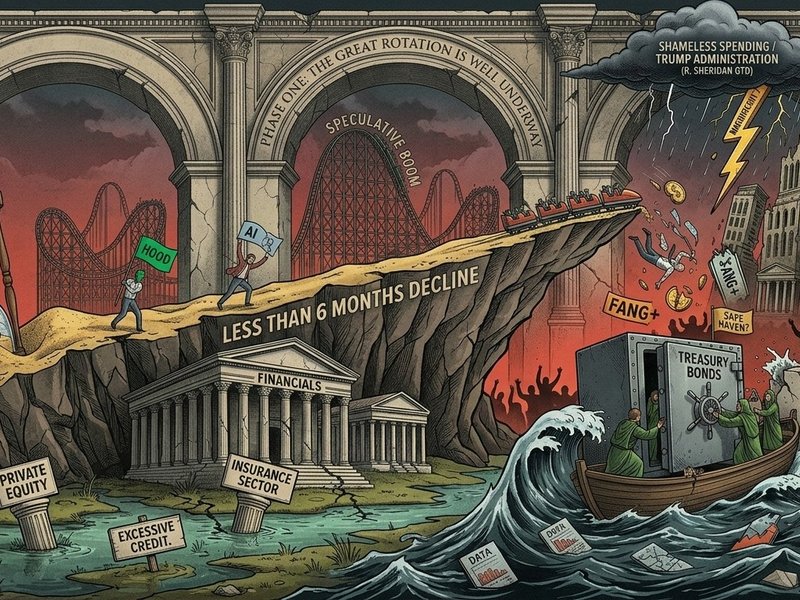
What I am driving home is the point that I expect a profit deflation to spread through most economic sectors because of new competitors, and to hit boom sectors, such as AI-related companies and semiconductors particularly hard.
Noteworthy in this regard is a recent analysis by https://asia.nikkei.com,which found that, “Five US tech giants' hidden debts soar to $1.65tn on opaque AI funding. Data center leases, GPU supply contracts raise liabilities at Meta, Oracle, the Nikkei study shows. Nikkei examined recent financial statements and other materials from Google owner Alphabet, Microsoft, Amazon, Meta, and Oracle. The five companies' hidden debt, which does not appear on balance sheets, totaled $1.65 trillion in the most recent quarter, exceeding the roughly $1.35 trillion in debt reflected on their balance sheets. Meta's off-balance-sheet debt is particularly high at about $420 billion, nearly triple its recorded debt.”
Most recently, one of the most prominent (and thoughtful) fund manager in the US (I have known him since my Drexel Burham days in the early 1980s), stated on TV that the MAG 7 companies (Apple, Microsoft, Alphabet, Amazon, Nvidia, Meta, and Tesla) were probably the best companies the US ever had. I have strong reservations about this statement, and even if it were correct, this insight does not guarantee that the MAG 7 stocks will perform well. After all, they have badly underperformed the S&P ex Mag 7 stocks since December 2024.
@HedgieMarkets noted that,” The Wall Street Journal reports (July 13) that multiple data center builders are simultaneously trying to sell majority stakes in their companies. Neutrality, DataBank, Edged, and EdgeCore are all working with bankers to find buyers this summer. DataBank alone could go for $25 billion. These aren't companies selling a few properties. They're selling control of their entire businesses to private equity while the AI buildout is supposedly booming. If AI data centers are the gold mine these companies have been telling investors they are, why are the people who built them racing to sell? The WSJ said they're ‘cashing in on a hot asset class.’ I'd read it differently. The people closest to the actual economics of building and operating these facilities all decided at the same time that they'd rather have someone else's money than their own equity. That looks a lot more like an exit than a diversification play.”
For the last 18 months or so, I have been continuously recommending to avoid the most popular sectors of the market, which included high-tech, Fang 7 and especially, semiconductor stocks. My main investment theme was to overweight value stocks and to underweight growth stocks. I continue to hold this view.
Last month, I noted that precious metals were entering a buying zone. I am still waiting for a clear buy signal, although mining stocks are in a base building mode.
I continue to like companies that are involved in necessities of life such as food, alcohol, and tobacco producer as well as casinos.
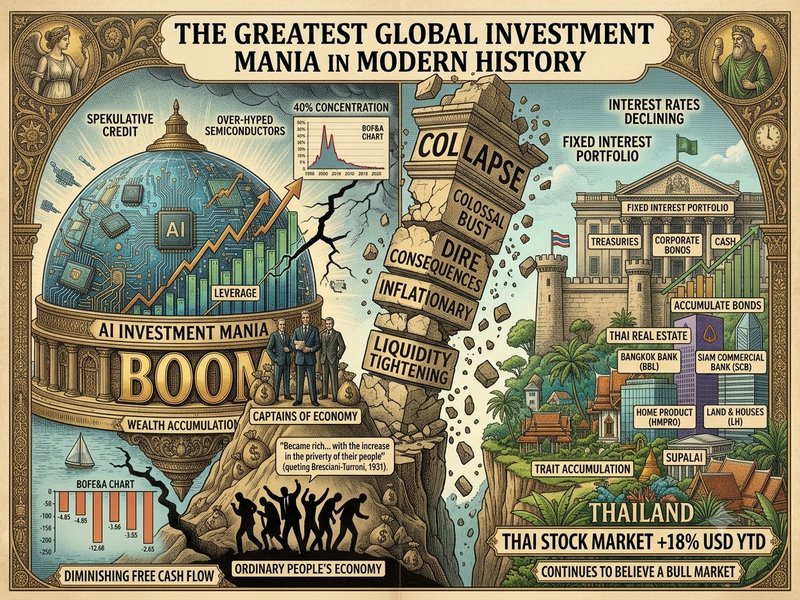
Given the colossal size of the AI-related capital spending boom and the leverage in the system, I am mindful of the words of the economist Gotfried Haberler who stated that,
“The length and severity of depressions depend partly on the magnitude of the 'real' maladjustments, which developed during the preceding boom and partly on the aggravating monetary and credit conditions.”
With kind regards
Yours sincerely
Marc Faber
Ready to get started?